Our Blog
Your Trusted Partner in Home Financing
A Quinte West Couple's Reverse Mortgage Story: Clearing Debt and Finding Cash-Flow Relief
November 3, 2026 | Posted by: Craig Nickerson
Last month, a Quinte West couple in their 60s came to us looking for something simple: breathing room, not a bigger bill. Between a home equity line of credit, a stretch of credit-card debt, and a list of renovations they'd been putting off, their retirement income was stretched thin before groceries and property taxes even came up.
Here's where they started:
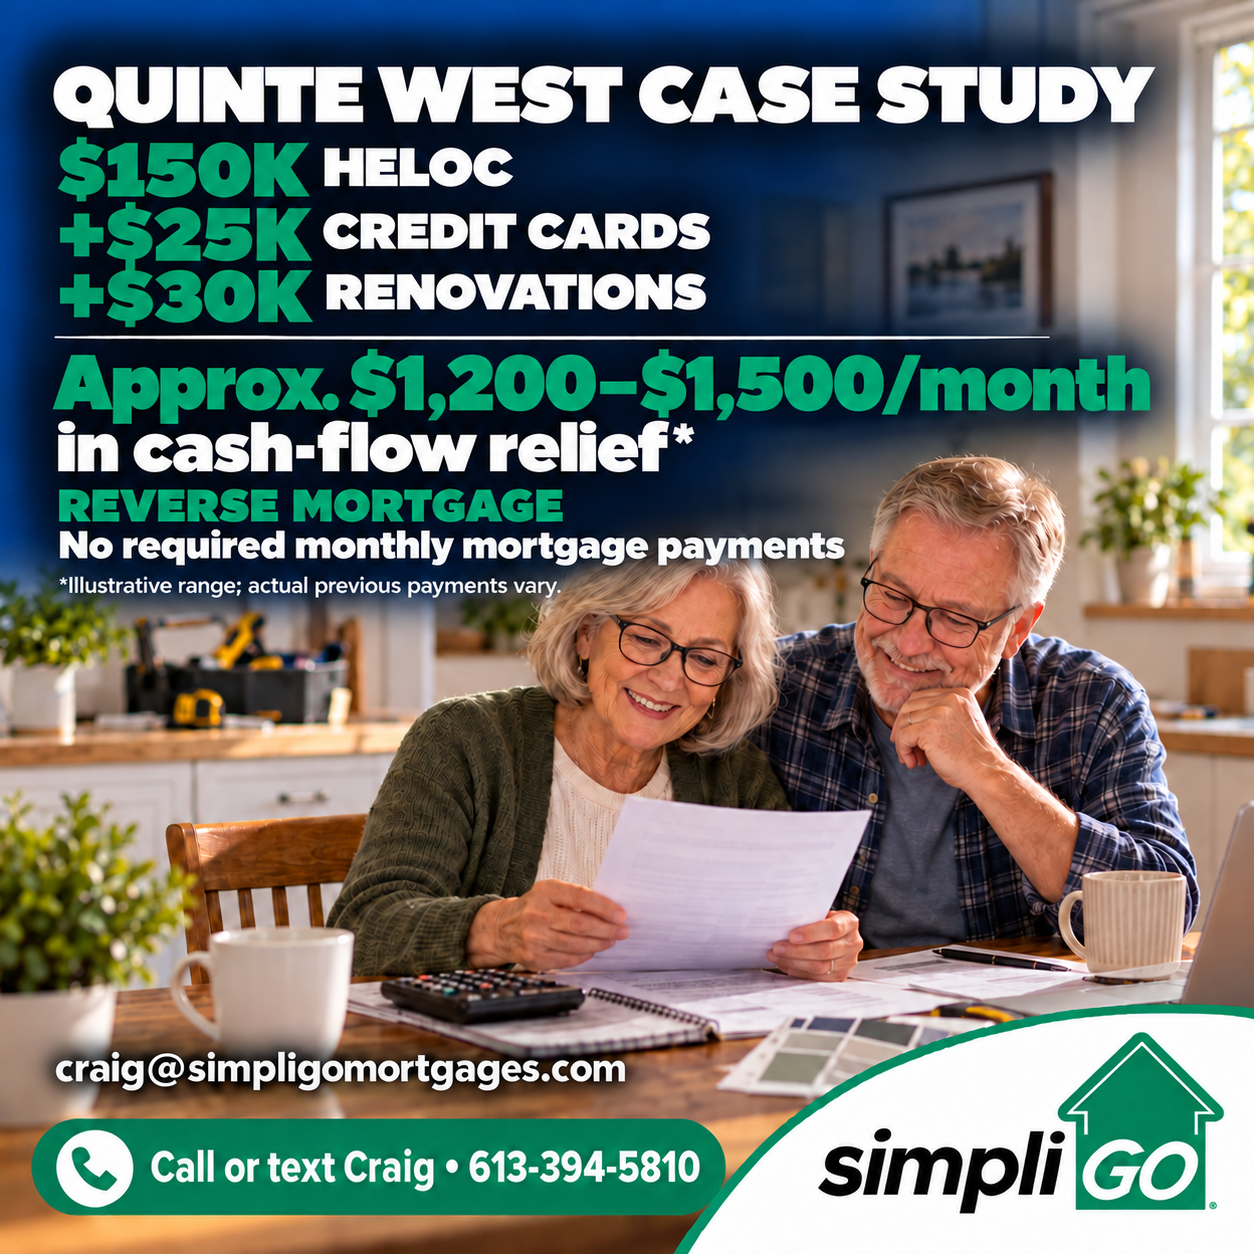
• A $150,000 HELOC, with interest-only payments eating into their monthly budget
• $25,000 in credit-card debt, carried at a much higher rate
• $30,000 in home renovations they needed but kept deferring
How a Reverse Mortgage Changed the Math
We arranged a $205,000 reverse mortgage that cleared the HELOC balance in full, paid off the credit cards, and set aside the $30,000 for renovations — all in one move. Because reverse mortgages don't require regular monthly payments, the debt that had been drawing down their income every month was gone.
What That Looked Like in Their Monthly Budget
Based on what they'd been paying toward the HELOC interest and credit-card minimums, we estimate this freed up roughly $1,200 to $1,500 a month in cash flow.* That's money that isn't going out the door anymore — it's staying in their household, covering day-to-day costs, and giving them some breathing room most retirees on a fixed income don't have.
The Bigger Picture
The renovations are getting done. The stress of juggling three separate debt payments on a pension is gone. And just as important, they're able to stay in the home and the community they've built their life in — rather than feeling pressured toward a downsize they didn't want.
To be clear: the debt didn't disappear. Reverse mortgage interest accumulates over time and reduces the equity left in the home down the road, so we walked through the long-term cost and the alternatives — a conventional refinance, downsizing, consolidating differently — before deciding this was the right fit for them. It won't be the right answer for everyone, but for this couple, trading debt payments for monthly breathing room made sense.
Is This You?
If you're a homeowner 55 or older in Trenton, Belleville, Quinte West or Prince Edward County carrying a HELOC, credit-card debt, or renovation costs on a fixed retirement income, it's worth seeing what the numbers actually look like for your situation — no pressure, no cost to find out.
Call or text Craig: 613-394-5810
craig@simpligomortgages.com
Learn more about reverse mortgages
Case details have been anonymized to protect client privacy. Savings shown are illustrative, based on this client's previous payments, and will vary by individual rate, balance and lender approval.
